What is the scope and industry significance of the Sport App Market?
Our analysis indicates that the Sport App Market is valued at 5.82 Billion in 2026, establishing itself as a vital digital infrastructure for global athletics. The sector encompasses mobile, wearable-integrated, and web software catering to consumers, professional franchises, and sports fans, driven by increasing smartphone penetration and the adoption of advanced fitness trackers.
Structural Growth Drivers and Market Restraints
Growth in the Sport App Market is propelled by surging demand for personalized fitness tracking and live streaming, alongside strict data privacy compliance challenges mandated by bodies like the European Union's GDPR. High development costs for augmented reality features act as a restraint, limiting smaller market entrants.
Emerging Trends Shaping the Sport App Market
The shift toward immersive technologies has accelerated, with companies integrating virtual reality and advanced performance analytics into training routines. Wearable-integrated applications from Garmin Ltd. and Fitbit Inc. lead this wave, bridging hardware ecosystems with cloud-based health analytics to enhance user retention.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic drastically disrupted traditional sports, accelerating a permanent migration toward home workout solutions and digital fan engagement. Peloton Interactive Inc. and Zwift Inc. capitalized on gym closures, creating a resilient recovery trajectory that permanently elevated baseline digital engagement across global consumer segments.
Competitive Benchmarking and Industry Concentration
The Sport App Market industry trends reveal a moderately fragmented landscape with high concentration among specialized innovators. Strava Inc. dominates the endurance tracking segment, while platforms like TeamSnap Inc. capture youth sports management, creating distinct moats through proprietary social graphs and localized network effects.
Executive Summary of the Sport App Market
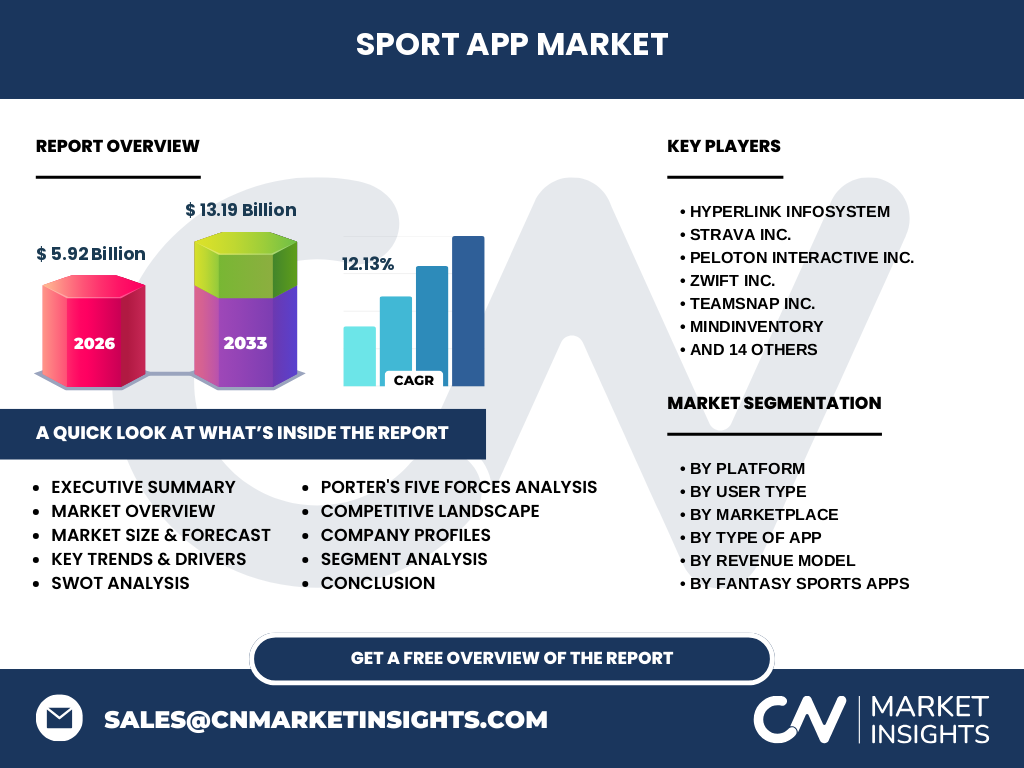
Our comprehensive research values the Sport App Market market size at 5.82 Billion for 2026, projecting an expansion to 13.19 Billion by 2033 at a 12.13% CAGR. Investment should target AI-driven personalization and wearable synchronization to capture high-margin subscription revenues.
Market Forecast from 2027 to 2033
Based on our research, the sector will surge from 5.82 Billion in 2026 to reach 13.19 Billion by 2033, exhibiting a robust 12.13% CAGR. This trajectory is anchored by expanding monetization via subscription-based models and the proliferation of 5G networks enabling low-latency live streaming.
Segmentation Analysis of Platforms and User Types
The market fragments across platforms including iOS, Android, and wearable integrations, serving diverse users ranging from casual consumers to professional athletes. Fitness and training apps dominate revenue generation, while fantasy sports and team management tools capture specialized engagement niches across global app stores.
Regional Market Analysis and Geographic Distribution
North America retains the largest revenue share due to high smartphone adoption and established sports entertainment ecosystems, followed closely by Europe. Meanwhile, Asia-Pacific represents the fastest-growing region, driven by expanding mobile-first populations and rising disposable incomes supporting digital health subscriptions.
In-Depth Regional Review
Regional performance highlights North America's dominance in fantasy sports monetization, whereas European markets prioritize cycling and running ecosystems championed by Strava Inc. Regulatory adherence, such as regional data localization laws, dictates how market players deploy cloud infrastructure across distinct geographic zones.
Strategic Positioning of Leading Companies
Key market participants employ distinct differentiation strategies; Freeletics GmbH focuses on AI-powered home workouts, while Agile Sports Technologies Inc (Hudl) captures elite athletic performance analytics. These players leverage targeted acquisitions and localized app store optimization to defend their competitive positioning.
Porter's Five Forces Analysis
Bargaining power of buyers is high due to abundant free fitness applications, while threat of new entrants remains constrained by high initial software engineering costs. Competitive rivalry is intense, forcing continuous feature innovation in live streaming and gamified community challenges to maintain user loyalty.
SWOT Analysis of the Sport App Market
Strengths include high consumer smartphone penetration and robust wearable integration. Weaknesses involve high customer acquisition costs. Opportunities lie in emerging AR/VR sports experiences, while threats stem from cybersecurity vulnerabilities and changing platform fee policies imposed by Apple and Google.
Value Chain Analysis from Development to End-User
The value chain flows from foundational cloud infrastructure providers and data API aggregators to application developers like MindInventory and Invoidea Technologies Pvt. Ltd., culminating in distribution via the Apple App Store, Google Play Store, and direct end-user subscription monetization.
Strategic Investment Insights and High-Potential Areas
Investors should focus on niche youth team and amateur league management tools such as SportEasy and TeamLinkt, which exhibit high retention rates. Subscription-based revenue models in nutrition and personalized coaching offer the most predictable recurring cash flows.
Conclusion and Key Takeaways
The Sport App Market analysis confirms a transition toward ecosystem lock-in, where apps seamlessly synchronizing with wearables outperform standalone tools. Sustained growth through 2033 relies on balancing freemium acquisition funnels with premium analytical features tailored for both professional and amateur demographics.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by combining primary stakeholder interviews with sports tech executives, secondary macroeconomic indicators, and app store download analytics from registries. This multi-tiered approach ensures high fidelity in market sizing and growth rate projections.
Scope of the Report and Coverage Parameters
This report covers global revenue streams generated by mobile, wearable, and desktop sports software across consumer and professional verticals from 2026 to 2033. Excluded from this scope are hardware manufacturing revenues, focusing strictly on software application monetization and platform service fees.
Recent Developments, Partnerships, and Strategic Moves
Recent industry momentum is defined by strategic acquisitions and API integrations between fitness apps and professional sports leagues. Companies like Heja AB and Spond AS have expanded their youth management footprints through localized funding rounds and enhanced messaging features designed for amateur sports coordinators.